💰 Beforepay Review – Pay Advance App in Australia: Costs, Pros & Real Cautions
👉 More info here: https://beforepay.sjv.io/vDg5QN
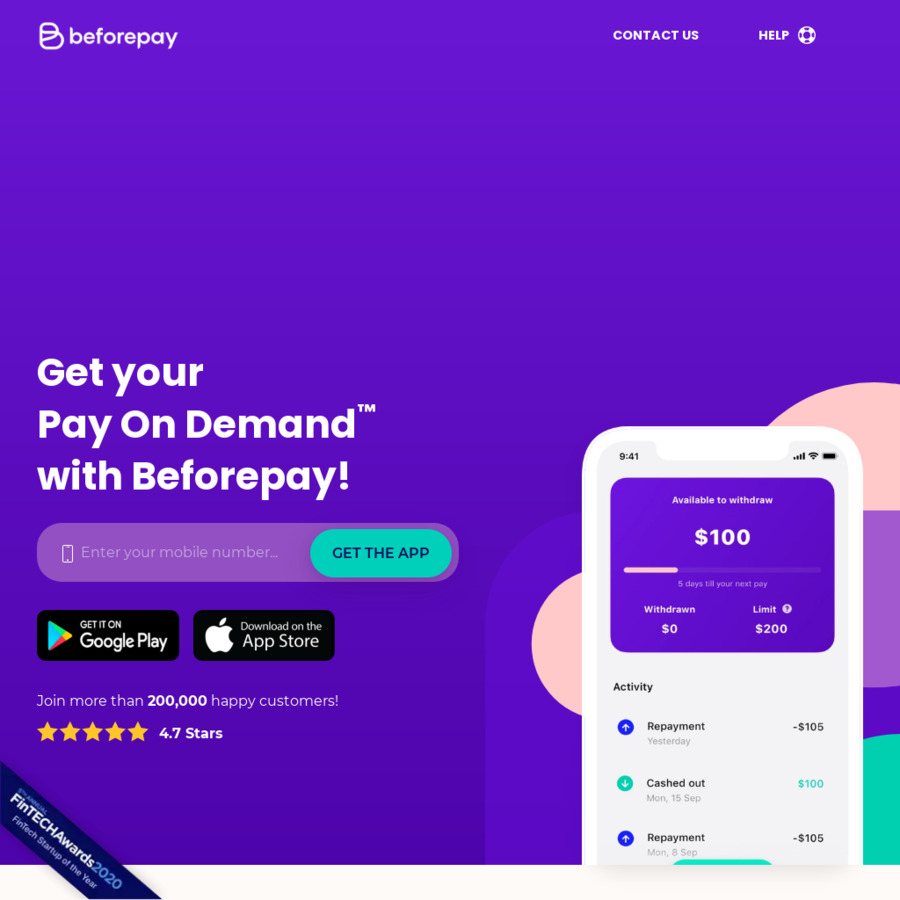
Beforepay is an Australian pay-advance app that lets eligible users access up to $2,000 of their upcoming pay (or Centrelink income) before payday, plus a separate Personal Loan product of up to $5,000. Before using it, here’s what the numbers and real user experiences actually show.


⚙️ How It Works & What It Costs
- Pay Advance — up to $2,000, charged a flat 5% one-off fee, plus up to 24% p.a. interest for some users based on risk assessment
- Personal Loan — up to $5,000, no hard credit check, comparison rate around 29.50% p.a.
- No traditional credit check for the Pay Advance product; Centrelink income accepted (up to 51% of total income)
- New users typically start with limits between $50–$1,000, scaling up with a consistent repayment history
⚠️ The Fee Looks Small — Until You Annualise It
This is the single most important thing to understand: that “just 5%” fee, repeated on a typical fortnightly repayment cycle, works out to roughly a 79% annualised rate — a figure multiple independent finance sites and CHOICE’s 2025 investigation have flagged as comparable to traditional payday loan costs, even though Beforepay isn’t legally classified as a payday loan.
📋 Regulatory Context
Beforepay operates under Australia’s pay-advance regulatory framework (ASIC Instrument 2026/199, effective March 2026) rather than under the stricter National Consumer Credit Protection Act that governs traditional loans — this is a real, structural reason the product can move fast with minimal checks, but it also means fewer of the consumer protections that apply to regulated credit.
💬 What Real Users Say
Genuine reviews are mixed. Positive feedback focuses on the app being fast and simple to use. But a recurring, serious complaint involves sudden, unexplained credit limit cuts — one long-term user described their limit dropping from $2,000 to $50 with no clear explanation despite a spotless repayment history, and reported unhelpful, generic responses from customer support when they asked why.
✔️ Pros
✔ Transparent, fixed 5% fee structure — you know the cost upfront, unlike hidden-fee traditional payday lenders
✔ Fast approval, no traditional credit check required
✔ Accepts Centrelink income, which many traditional lenders exclude
✔ Useful for a genuine one-off, short-term cash flow gap you can repay on payday without issue
✖️ Cons to Consider
✖ The effective annualised cost (~79% on repeat fortnightly use) is a serious number to weigh, even though each individual fee looks small
✖ Real user reports of sudden credit limit reductions with little explanation or support responsiveness
✖ Financial commentators (including Canstar’s editor-at-large) describe repeated use as a “band-aid solution” that can mask a deeper cash-flow problem rather than fix it
✖ Not suitable if you can’t confidently repay by your next payday — repeated borrowing compounds the cost quickly
💬 Final Verdict
Beforepay can be a fast, transparent option for a genuine one-time cash-flow gap you’re confident you can repay next payday. But this is a form of short-term borrowing, not free money — the real annualised cost is much higher than the “5% fee” headline suggests, and it’s worth treating as a last resort rather than a regular habit. If you find yourself needing it every pay cycle, that’s worth taking as a signal to look at the underlying budget gap rather than the app itself.
This is general information, not financial advice. If you’re regularly short before payday, a free service like the National Debt Helpline (1800 007 007) can help you look at options with no cost or credit impact.




Reviews
There are no reviews yet.